“On Retirement Income” series:
- A 4% Rule Fable
- The 4% Rule Launches a Bigger Discussion
- From Mindless Inconsistency to Mindless Consistency
- Stock/Bond Portfolios and Sequence-of-Returns Risk
- Goals-Based Investing Starts with Goals
- Guaranteed Income Sources (Social Security, Etc.)
- How Guaranteed is Guaranteed Income?
- Get Real Income by Getting TIPSy
- TIPS Q&A
- Flexible Spending, Can you DIG It!
- Flexible Spending Alternatives
- More to come…
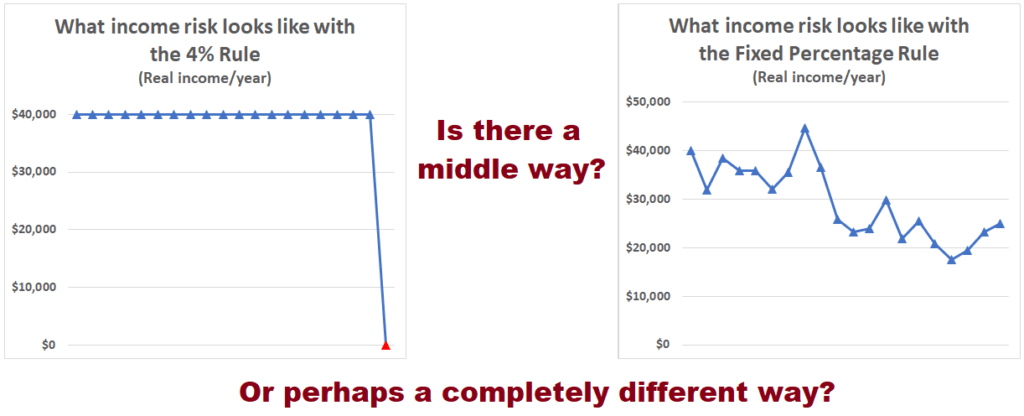
In our last article in this series, we built a stock/bond portfolio for our fictional friends Bob and Barbi, to cover the “flexible” portion of his annual spending budget. We did this using Round Table’s “Dynamic Income & Growth” (DIG) model, which uses systematic rules to ratchet spending up or down in future years in response to market performance—unlike the 4% Rule—but does so in a less volatile manner than the wildly varying income produced by the Fixed Percentage Rule. I.e., DIG is our answer to the “middle way” question posed in this chart:
We were able to cover the year-1/age-65 $21,300/year flexible spending goal from Bob and Barbi’s budget by placing $532,500 of their assets in a DIG portfolio. We then showed them high/median/low modeled outcomes for future real and nominal (i.e., inflation-adjusted and non-inflation-adjusted) income from this portfolio. There’s lots of ground to cover in this installment, so we’re not going to summarize the details here when you can read them for yourself there.
Building Bob’s portfolio left sufficient assets for additional goal coverage, which is a topic we’ll discuss in future articles…and at the rate we’re churning out these articles, admittedly that could be a rather far future indeed, but that’s because we prefer to spend our time building real retirement plans and portfolios for real clients! (Nice spin there, eh? If you’re a real person, you can get much faster service than Bob and Fred by reaching out to us here.)
A Problem for Fred
Meanwhile, though, when it comes to Bob’s twin brother Fred, things are not so simple. The “Non-Required/Flexible” portion of his budget calls for about $25,100 of income.[1] Using the same conservative “standard” DIG parameters[2] that we employed for Bob, a year-one 4% withdrawal rate at age 65 would require a $660,000 portfolio of stocks and bonds to support that much cash flow. But after placing ~$225,000 in an “inflation-protected income” (IPI) TIPS ladder portfolio to build Fred’s Social Security bridge, only about $570,000 of Fred’s initial $796,000 worth of investable assets remain unallocated. If we placed the entire remaining amount in a standard DIG strategy, his DIG spending would only be ~$22,800. Fred’s total year-one retirement cash flow would fall about $2,300 short of his rather modest $70,500 goal, despite leaving no additional assets to cover emergency spending or other goals.
Not ideal! But where lesser models would give up in despair,[3] the Layer Cake system kicks things into overdrive to find solutions for Fred.
Give Us a Smile
An important concept that helps us arrive at a solution to Fred’s dilemma is the fact that most retirees want to spend more in the early years of retirement—e.g., 60s and at least early 70s, when health and vitality facilitate travel and adventure—than in later years—80s and 90s, when Father Time commands most people to slow things down.
Perhaps the best-known exploration of this general observation is the so-called “retirement spending smile” study by retirement researcher David Blanchett. In his article Exploring the Retirement Consumption Puzzle,[4] Blanchett concluded that the average retiree’s real (i.e., inflation-adjusted) consumption tends to decline year-over-year throughout retirement. When he applied a polynomial regression to the raw data, the pattern of annual real spending decline follows what he called a “retirement spending smile” pattern, as seen in the age 60 to age 85 dotted curve in this figure from his paper:
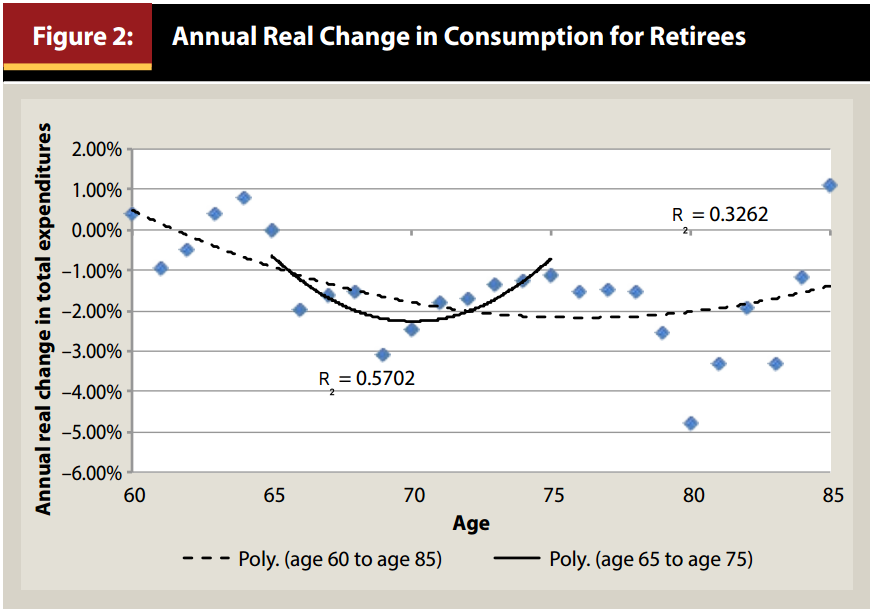
Notably, the upward-curving right side of the smiley shape is driven by late-in-life health expenditures, and Blanchett concluded in a recent follow-up research paper[5] that that average is greatly affected by outlier spending among those with the most unfortunate healthcare and long-term care outcomes, such that the median retiree may see more of a “smirk” pattern, where the rate of real spending continues to decline at an accelerating or at least constant rate even in the later years of retirement. The long-term care outlier is a topic we will discuss down the road and up the Layer Cake.
For now, the important conclusion is that the typical retiree is likely to want to spend more early in retirement and less later, on an inflation-adjusted basis. This doesn’t necessarily imply less spending over time on a nominal (i.e., non-inflation-adjusted) basis, but it does suggest that targeting approximately constant annual real spending may be too conservative.
Moreover, because the bedrock allocation to Social Security provides constant real income, a 1%/year reduction in total real income (the approximate retiree population average noted by Blanchett in his paper) could be manufactured by combining the non-reducing Social Security income with a much faster reduction in “flexible” income.
Alternative #1: DIG deeper
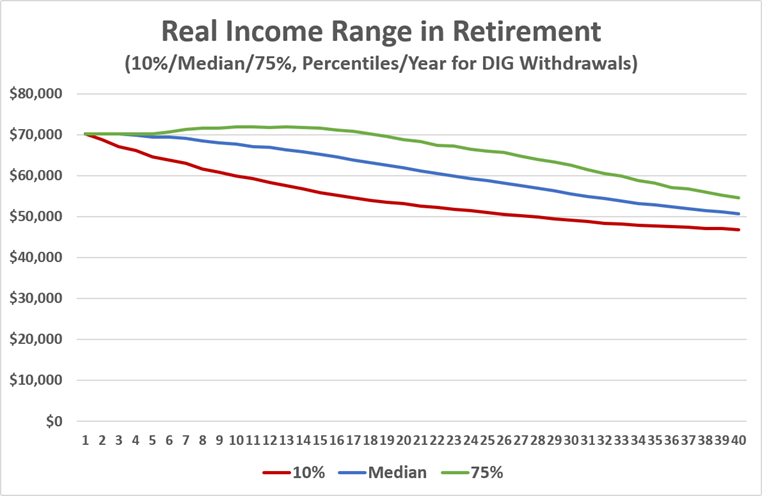
Our baseline DIG methodology targets end-to-end stable real cash flow in the median case, given moderate, forward-looking expected[6] market return and volatility estimates. We acknowledge that this makes our default parameters rather conservative, and many researchers, including David Blanchett himself, recommend higher year-1 withdrawals from a stock/bond portfolio, in combination with flexible spending rules. This is a sensible argument, and the only reason we don’t default to more aggressive initial spending is that half the outcomes are worse than the median (math!!!), and the more aggressively you spend in the early years, the uglier the bad-path outcomes can get. Nonetheless, given the magnitude of Fred’s flexible spending goal and his lack of a legacy motive,[7] we are happy to show him modeled outcomes from simply targeting a higher spending rate in his DIG portfolio. For example, below is a total real income chart for a version of the DIG model starting at a 6% withdrawal rate instead of 4% at age 65. Thanks to the higher starting draw, the initial portfolio requires only $418,000 to build.
(Source: Round Table calculations.)
Due to the aggressive initial spending rate, the median (blue) line corresponds to Fred’s annual inflation-adjusted DIG income dropping from about $25,100/year to about $10,350/year by age 95, which is nearly a 3% annualized decline over 30 years. However, when combined with the constant real-dollar income from Fred’s “IPI Model” TIPS bridge plus Social Security income, his total combined real income declines by about 0.8%/year, from ~$70,500 to ~$55,500.
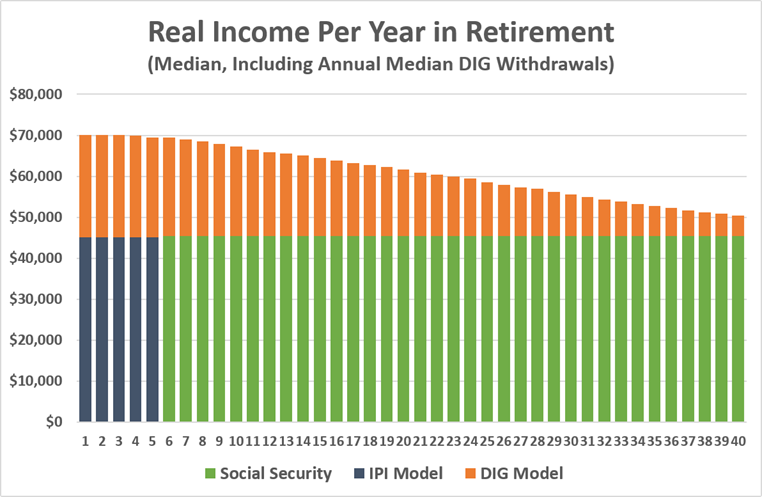
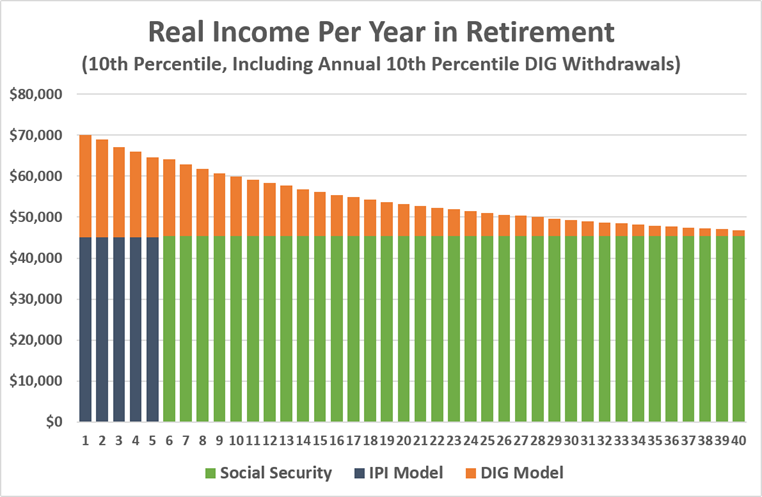
The problem, again, is that red line. In that 10th percentile (“bad markets”) model outcome, Fred’s income drops to ~$55,500 in just 16 years—age 81 instead of age 95 in the median (“normal markets”) outcome.
And as we noted in the last article, the dynamic withdrawal rules (the “D” in “DIG”) mean that even a “median-ish” real-life income experience will have some unpredictable volatility along the way.
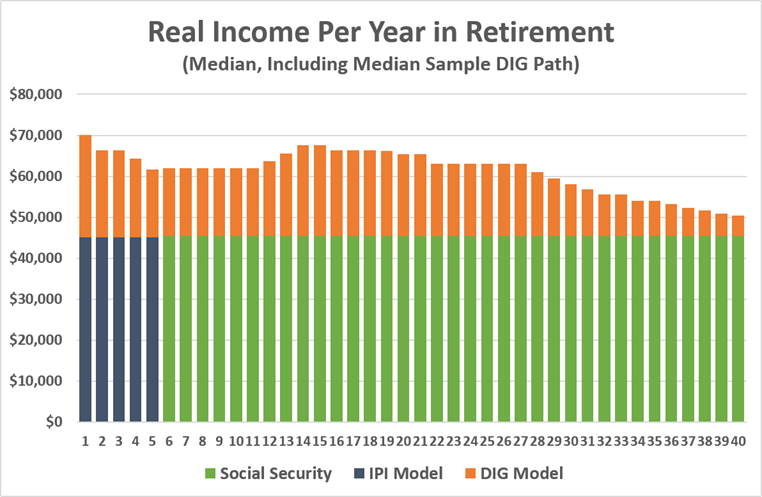
Importantly, this volatility is bidirectional, and significantly more positive outcomes are possible, and perhaps even more likely than the negative outcomes highlighted above. Nonetheless, this is more income risk than Fred feels willing to bear, so we proceed to another option.
Alternative #2: Annuities again!
We previously discussed annuities in “Layer 1” of Round Table’s Layer Cake model, because in one sense they can be viewed as bedrock income: A guaranteed paycheck for life. (Also see here about the credibility of the guarantee/guarantor.)
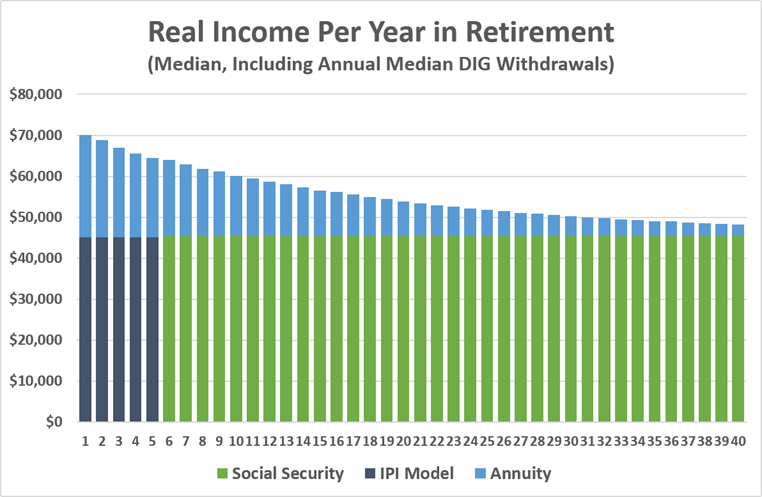
But in a different sense, annuity income is a great fit up here in Layer 3, “flexible income” territory. Why? Because a fixed nominal annual income rather resembles the slowly-ish declining real income someone like Fred or any spending-smiler may be looking for as a Social Security supplement. What’s more, to buy the target $25,100/year of income in fixed nominal annuity payout form is cheaper still. As of this writing (August 2026), for just a single-life payout—since Fred does not have a spouse who also needs income coverage for life—an annuity product with a 7.8% payout rate is available. Consequently, it would only cost Fred about $322,000 to generate the target $25,100 of nominal income. The resulting inflation-adjusted total cash flow would look something like this:
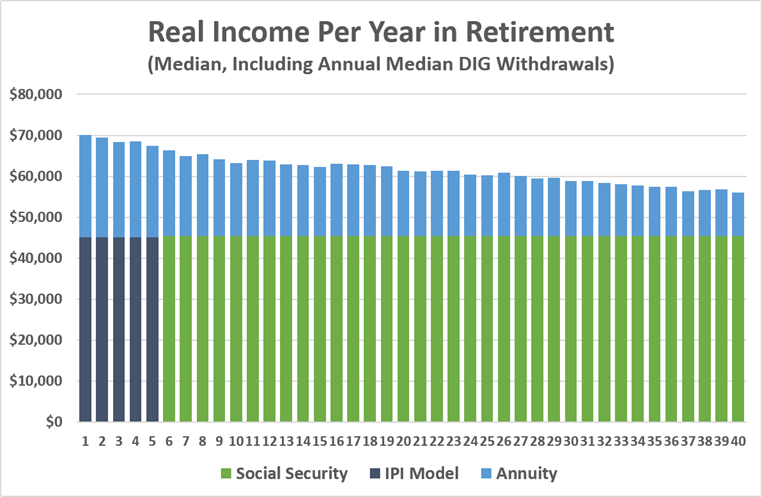
Annuitized income eliminates the market-based riskiness of the DIG model, in exchange for eliminating the “G” element: I.e., the potential for growth on Fred’s portfolio value and annual income. The annuity does still carry inflation risk, but if inflation comes in around 3%, then the resulting annual decline in real income from an annuity plus Social Security would be in the 1%-ish range we’re targeting for Fred.
A prolonged stretch of higher-than-expected inflation is the biggest risk to a nominal annuity income stream.[8] An annual inflation rate around 6% would match the 10th percentile DIG outcome in reducing Fred’s total real income to about $55,500 in just 16 years.
An interesting theoretical question to which we do not profess to know the answer is whether the odds of 16 years of 6%+ inflation are higher or lower than 10%. Odds are good that high inflation and poor real returns for stocks and credit bonds would be somewhat correlated events anyway. Nonetheless, the annuity eliminates the year-over-year, guardrails-driven income volatility of the DIG model.
However, the assets in an annuity with a generous income rider, like the one we’ve shown Fred, are probably best viewed as gone. If Fred gets hit by a bus shortly after he pays for the annuity, his heirs will get the balance in the contract. But if he lives anywhere near or beyond life expectancy, that cash value will be zero, despite the payout continuing for life. And if he pulls extra money out of the contract at any point, the consequences for the annual payout are punitive; we will do everything in our power to find other options for Fred if he needs extra cash. (See as-yet-unwritten articles in this series covering the retirement emergency fund, for example…or see the emergency fund section of this article.) But remember! Fred saves about $96,000 with the annuity vs. a DIG portfolio with even a 6% initial draw; those savings could be a pretty snazzy starter for that emergency fund.
Alternative #3: The “Go-Go” Bond Ladder
Another common method of describing the phenomenon encapsulated by the spending smile is to divide retirement into three phases: An approximately thirty-year projected retirement might be divided into ten “Go-Go”, ten “Slow-Go”, and ten “No-Go” years. The Go-Go years are the healthiest and most active years that produce the highest targeted spending.[9] The Slow-Go and No-Go years each involve incrementally decreasing adventurous activity, but in the no-go years, the risk of elevated medical and long-term care spending spikes, as seen in the right side of the spending smile.
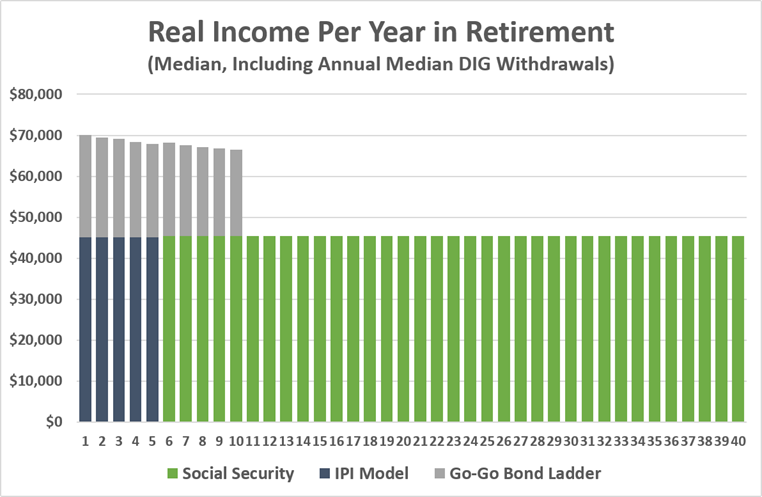
In light of this concept, another tool in Round Table’s toolbelt is a nominal bond ladder to create income for the enjoyable activities of the Go-Go years. Mechanically, a nominal bond ladder is the same as the TIPS ladder that lives in Layer 2 (see here for greater detail on the mechanics), except that instead of building inflation-protected income, the “rungs” produce a constant stream[10] of nominal income. The idea here would be to craft the $25,100 for the first 10 years, with a plan to revisit how many additional years of (perhaps lesser) additional income are required thereafter.[11]
Because this approach covers a limited number of years instead of Fred’s lifetime, it can be purchased even more cheaply than the annuity. It is also less expensive than an equivalent TIPS ladder, primarily because the latter includes payment for inflation protection, but also because a nominal ladder—especially for flexible expenses—can be constructed from bonds that pay a higher yield in exchange for a small amount of credit risk.[12] Even highly-rated bonds from stable corporations are higher-yielding than their US government counterparts.
For example, at present[13] a 10-year, $21,100/year ladder of income from nominal bonds could be constructed at the cost of about $200,000. The resulting bond ladder real income chart looks like the annuity example for the first ten years, followed by a dropoff to nothing:
(Source: Round Table calculations.)
If we pulled the annuity up from Layer 1 (guaranteed income sources) to Layer 3 (flexible income sources), we’ve essentially pulled the nominal bond ladder—a classic “additional goal” tool—down from Layer 4 (growth plus additional goal targeting) into Layer 3 for the same reason: It’s a practical alternative mechanism for covering flexible budgetary cash flow requirements. And while the cliff is a distinct retirement income planning eyesore, don’t forget that the measly ~$200,000 price tag would leave a whopping $370,000ish for Fred to use toward other Layer 4 goals and/or future Layer 3 income.
Alternative #4 (or perhaps “Alternative #1/2/3, Go-Go”): Mix-N-Match!
There is nothing mutually exclusive about these alternatives! For example, a Layer Cake proposal that crafts the entire flexible spending budget as a 10-year ladder followed by a cliff to nothing—alternative #3 above—is not something we would typically propose to a real-life client. (Being a fake client, Fred is unoffended.) Rather, we would usually pair a DIG strategy and/or an annuity with a Go-Go bond ladder.
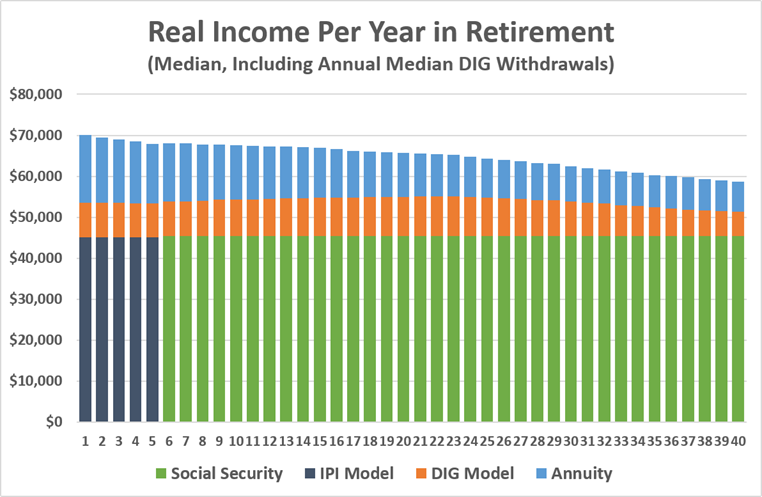
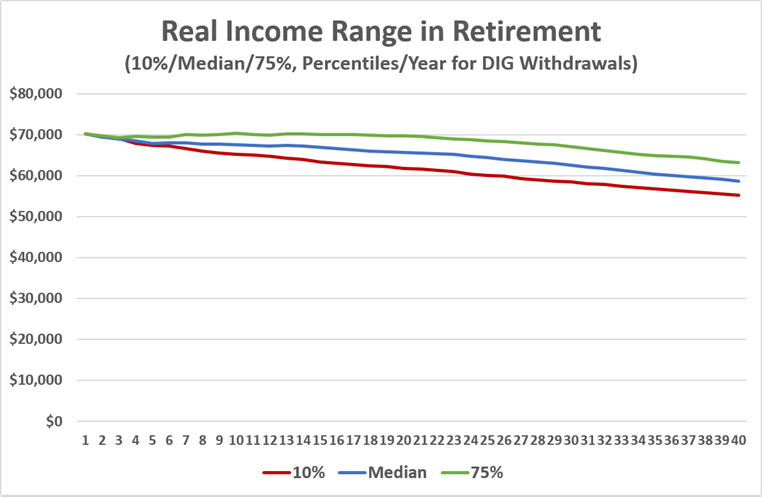
After walking Fred through the various options, we work together to craft a combination that he feels is a good balance between competing objectives, splitting his flexible income dollars evenly between an annuity (for cost-effective nominal income) and a DIG portfolio using the standard withdrawal rules. We find that balance at around $212,500 apiece, with the annuity providing ~$16,600 and the DIG portfolio providing ~$8,500 of income initially.
(Source: Round Table calculations.)
Here is a rundown of the balance of attributes that Fred finds appealing with this combination:
- The annuity provides significantly more income in the early years of retirement, but its flat nominal income almost certainly implies declining buying power over time, and the cash value must be viewed as an untouchable and rapidly depleting asset.
- The DIG portfolio will maintain at least some portfolio value—barring extreme longevity or extraordinarily weak market returns—and it offers the potential to maintain or even grow real income, but the cash flow it produces is smaller initially and will be more volatile.
- Fred understands the “spending smile” concept, but he is more concerned about the downside of an uncomfortably rapid decline in spending power than he is about the upside of having too much available to spend. With this selection, the 10th percentile outcome shows a slightly more gradual real income decline than does the median outcome of the 6% DIG option, with far less volatility as well.
- The selected combination costs about $425,000—just slightly more than the much more volatile “Alternative #1” (the DIG portfolio with a 6% starting draw)—and this leaves a healthy ~$145,000 for Fred to use towards additional goal targeting, including a retirement emergency fund.
We’ll look at those “Layer 4” additional goals in a couple articles, but our next installment will answer some questions about the admittedly complicated topics we’ve covered in this article and the one prior.
[1] This comes from his total budget target of $70,550 minus his Social Security benefit of about $45,450. Notably, Social Security will cover somewhat more than the “Required/Inflexible” spending target of $44,150 from his retirement budget. By the way, you may have wondered why we would take spending that is flexible by definition and target it with such precision as to produce, say, $25,100 of income instead of, say, $25,000 or $26,000, or whatever? The answer is that we generally wouldn’t. In fact, after we have our clients build out their retirement planning budget, we often recommend building in some additional cash flow, both as a cushion against overly conservative spending targets and a way to nudge certain investors to enjoy their retirements a little more. And when we do that, we’ll naturally round the numbers out a bit. Not that there’s really any benefit to generating round-number cash flow, especially given that the numbers will un-round in future years, due to CPI adjustments, DIG guardrails, etc. But it helps to avoid the illusion of false precision in what is inevitably an inexact science—our best efforts to the contrary notwithstanding.
[2] To the extent there is such a thing as “standard” DIG parameters. We’re all about personalization, including in the nitty gritty details of flexible spending from a stock/bond portfolio! But as we discussed in the last article, we find it’s often preferable not to overwhelm client modeling exercises with too many free variables unless there is a goals-based reason to investigate modifying some of them…as indeed there is with Fred’s situation.
[3] Okay, joking aside, there are times when someone’s retirement spending goals are simply unrealistic given the assets available to cover the desired cash flows. We will not withhold such truths from clients and prospects who work with us, but we will discuss various options to bring the goals and the assets into better alignment.
[4] Blanchett, David, “Exploring the Retirement Consumption Puzzle”, Journal of Financial Planning, May 2014, https://www.financialplanningassociation.org/sites/default/files/2020-09/MAY14%20JFP%20Blanchett_0.pdf.
[5] Blanchett, David, “How Spending Evolves in Retirement: A Smile, A Smirk, or Something Else?”, Financial Planning Review, 15 June 2026, https://onlinelibrary.wiley.com/doi/10.1002/cfp2.70032.
[6] As everywhere in our writings, the unfortunate but universal term “expected return” refers to statistical expectation, not to a return you can “expect” to get!
[7] Surely we mentioned Fred’s lack of a legacy motive before, right? Right?!!
[8] This is an annoying inefficiency. Conceptually, an annuity income provider could use inflation swaps to trade out “fixed nominal” for “inflation minus ~2.5%-3%”, for the same up-front cost, as I explained here.
[9] For a poignant discussion about making the most of the “Go-Go” years, see Dan Haylett’s article, Your 12 Good Years. Though also, see the new Yale study suggesting that many older adults experience increasing health and vitality well into their 70s, population averages notwithstanding.
[10] Or any other pattern, but a constant stream is a common use case.
[11] As per the prior footnote, another option might be to build, say, half that nominal amount for the next 10, Slow-Go, years.
[12] Side note (er…foot note): A fixed term/“period certain” annuity can serve much the same purpose.
[13] Again, as of this writing. I keep mentioning this because, like annuities, the cost varies inversely with interest rates. I mention it with greater urgency because interest rates at present are much higher than they have been for most of the past 15-20 years, though of course there is nothing to say they couldn’t go even higher.
DISCLOSURES: All content is provided solely for informational purposes and should not be considered an offer, or a solicitation of an offer, to buy or sell any particular security, product, or service. Round Table Investment Strategies (Round Table) does not offer specific investment recommendations in this presentation. This article should not be considered a comprehensive review or analysis of the topics discussed in the article. Investing involves risks, including possible loss of principal. Despite efforts to be accurate and current, this article may contain out-of-date information; Round Table will not be under an obligation to advise of any subsequent changes related to the topics discussed in this article. Round Table is not an attorney or accountant and does not provide legal, tax or accounting advice. This article is impersonal and does not take into account individual circumstances. An individual should not make personal financial or investment decisions based solely upon this article. This article is not a substitute for or the same as a consultation with an investment adviser in a one-on-one context whereby all the facts of the individual’s situation can be considered in their entirety and the investment adviser can provide individualized investment advice or a customized financial plan.
The data shown in this article is for informational purposes only and should not be considered as an investment recommendation or strategy, or as an offer to buy or sell any particular security, product, or service. Past performance may not be indicative of future results. While the sources of data included in any charts/graphs/calculations are believed to be reliable, Round Table cannot guarantee their accuracy.